
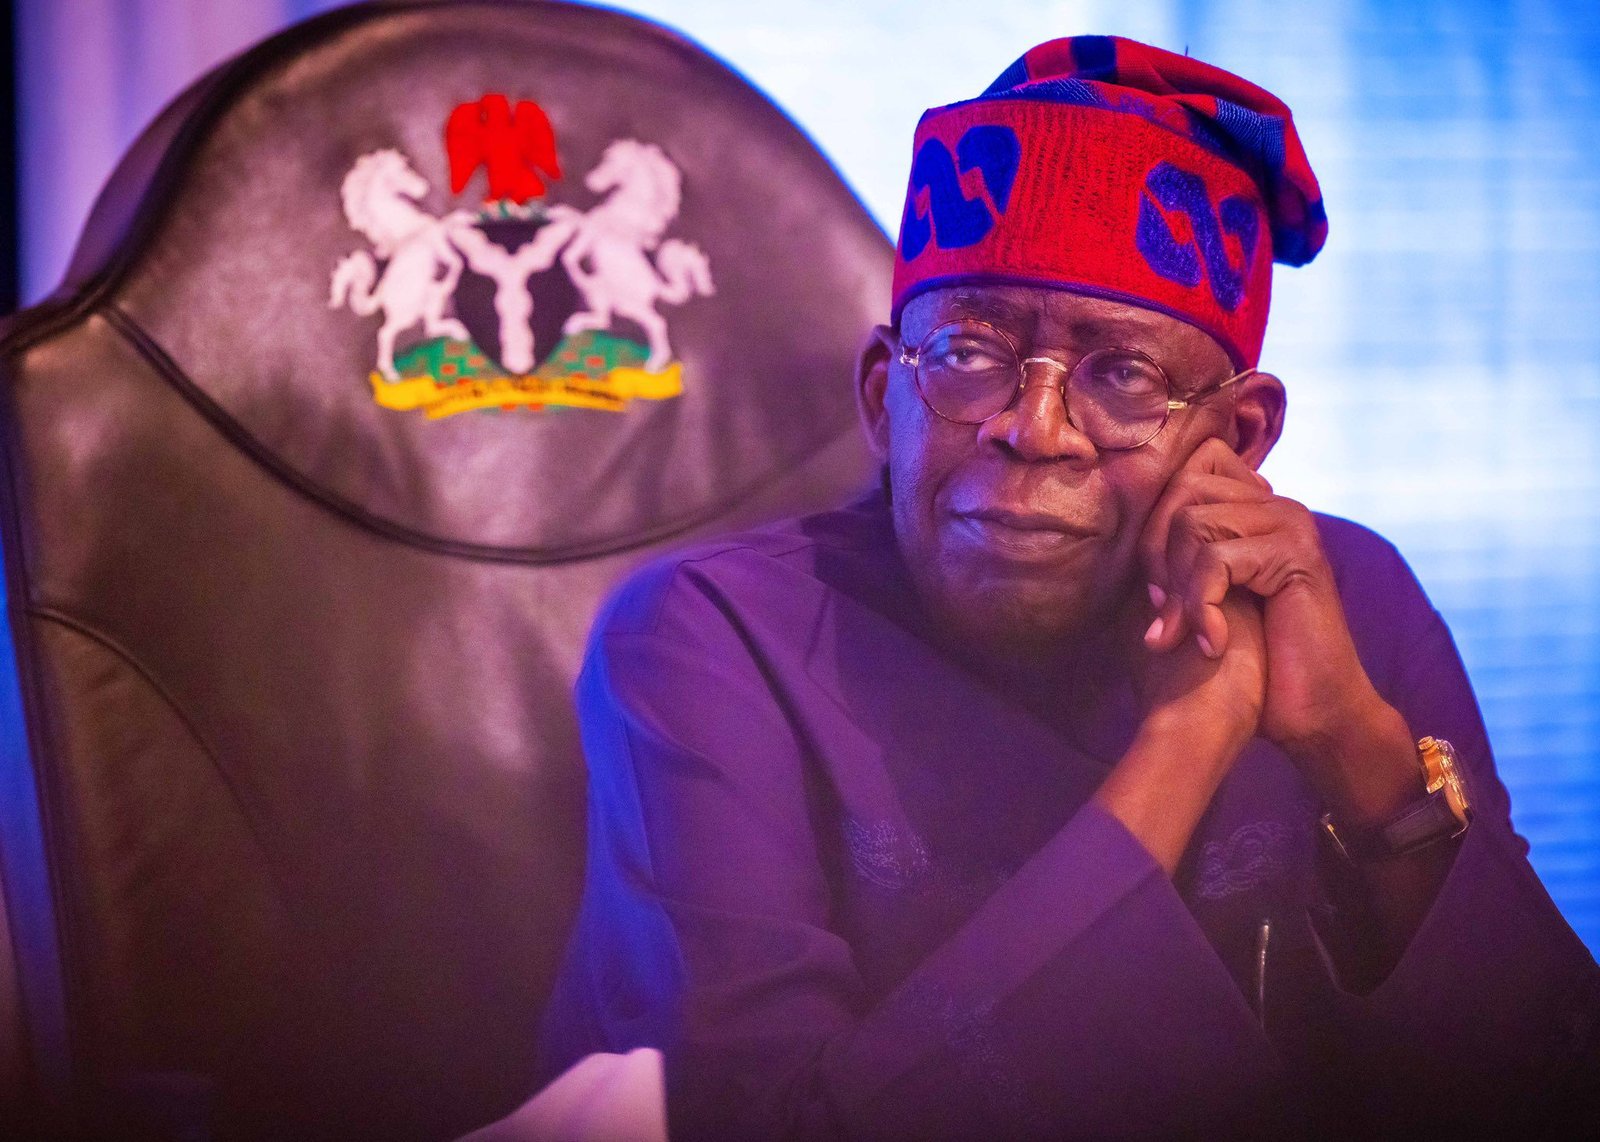
President Bola Tinubu has defended his administration’s plan to secure fresh foreign loans, arguing that Nigeria needs long-term investment in infrastructure to achieve its ambition of building a $1 trillion economy by 2030.
Tinubu said the proposed borrowing would fund major infrastructure projects, including highways, electricity improvements and port upgrades, which he believes would create jobs, expand businesses and stimulate economic growth.
His defence comes amid criticism from the Nigeria Labour Congress (NLC), which has questioned the need for additional borrowing despite the Federal Government’s claims of increased revenue following the removal of petrol subsidy.
The government has asked the National Assembly to approve fresh external loans totalling $20.5 billion and €1.45 billion.
In a statement titled From Reforms to Delivery: Our Infrastructure Investment and Growth Strategy, Tinubu argued that the debate should focus on what borrowed funds would achieve rather than the amount being borrowed.
“The key question is not how much we borrow, but what we build, the value we create and the future we leave behind,” he said.
Tinubu lists projects to receive loan funding
The President identified the Lagos-Calabar Coastal Highway, Sokoto-Badagry Superhighway and Trans-Sahara Superhighway among the major projects the government plans to finance.
He also listed improvements to the national electricity grid and upgrades to major commercial ports in Lagos.
According to him, the projects would connect economic regions, reduce transportation costs, support agriculture and industries, and attract private investment.
Tinubu said the Lagos-Calabar Coastal Highway alone could reduce transportation costs along its route by between 15 and 20 per cent.
He also projected that the project could contribute up to two per cent to Nigeria’s Gross Domestic Product through increased trade, tourism and industrial activities.
The President estimated that the highway would generate about 100,000 direct jobs in construction and engineering, alongside more than 150,000 indirect jobs in logistics, building materials and related services.
“We are building more than highways. We are opening economic corridors, connecting markets, supporting industries and reshaping Nigeria’s economic geography,” he said.
Tinubu maintained that Nigeria could not achieve its $1 trillion economic target by 2030 without significant improvements in infrastructure.
“We cannot build a $1 trillion economy with infrastructure designed for an economy a fraction of that size,” he added.
President highlights economic improvements
Tinubu also defended the borrowing plan by pointing to improvements in some economic indicators since his administration introduced major reforms in May 2023.
He cited he removal of petrol subsidy, exchange rate unification, tax reforms and measures to control inflation as steps that had improved government finances and the wider economy.
According to the President, Nigeria’s economy grew by 4.43 per cent in the second quarter of 2026, while headline inflation declined to 14.63 per cent in September from 20.98 per cent in the corresponding period of 2025.
He said the country’s gross external reserves stood at $55.1 billion as of October 9, 2026, including approximately $46 billion in net reserves.
Tinubu further stated that Nigeria’s tax-to-GDP ratio had increased from seven per cent to 12.5 per cent.
He also said net allocations from the Federation Account Allocation Committee (FAAC) rose by 44 per cent, from ₦15.2 trillion in 2024 to ₦21.9 trillion in 2025.
The President argued that these developments had strengthened investor confidence and improved Nigeria’s access to international financing.
He cited positive assessments from global credit rating agencies, Nigeria’s return to Frontier Market status and its successful Eurobond issuance as evidence of improving financial credibility.
Tinubu said the government was pursuing longer-term loans with repayment periods that correspond with the lifespan of the projects being financed.
According to him, this approach would reduce pressure from frequent repayments and help Nigeria secure more favourable borrowing terms.
Tinubu acknowledges debt servicing concerns
Despite defending the proposed loans, the President acknowledged the need for responsible borrowing and spending.
He disclosed that public debt stood at 35.75 per cent of GDP in the second quarter of 2026, while debt servicing consumed about 65 per cent of government revenue in the first half of the year.
Tinubu said the Federal Executive Council’s economic plan included avoiding the printing of money to finance budget deficits and preventing spending commitments that were not backed by available funds, particularly during the pre-election period.
He maintained that the success of the borrowing plan would ultimately depend on whether the projects were completed and delivered measurable benefits to Nigerians.
“Securing financing is only the beginning. The real achievement lies in completing projects, delivering value for money, and improving Nigerians’ lives,” he said.
NLC questions fresh borrowing despite increased revenue
The Nigeria Labour Congress, however, has challenged the Federal Government to explain why it continues to seek foreign loans despite claiming that the removal of petrol subsidy has increased revenue.
Speaking on Channels Television’s The Morning Brief, NLC President Joe Ajaero questioned the justification for continued borrowing from international financial institutions, including the International Monetary Fund and the World Bank.
“If you come out to tell us that subsidy is gone, that you are making more money and then you are giving more money to states, what is the justification for continually borrowing from the International Monetary Fund and the World Bank and other agencies when there is enough money?” he asked.
Ajaero also argued that rising international crude oil prices should prompt the government to reconsider its borrowing plans.
He noted that the 2026 budget was based on an oil price benchmark of $70 per barrel, while crude prices had risen above $100 per barrel following tensions involving the United States and Iran.
“If the 2026 budget was prepared with crude oil price benchmarked at $70 per barrel and now sells above $100 per barrel due to the US-Iran crisis, should this country still be taking loans?” he asked.
The labour leader questioned the impact of additional borrowing on Nigeria’s debt burden, arguing that higher oil earnings and increased allocations to oil-producing states required the government to explain its need for more loans.
However, Ajaero clarified that the NLC had no constitutional or institutional authority to approve or reject government borrowing. He said such decisions rested with the relevant government institutions.
He urged Nigerians and relevant agencies to demand greater accountability from the Federal Government over the proposed loans.
The disagreement highlights the competing arguments surrounding Nigeria’s borrowing strategy: the government says long-term financing is necessary to address infrastructure gaps and expand the economy, while organised labour is demanding clearer explanations for continued borrowing amid claims of rising public revenue.