

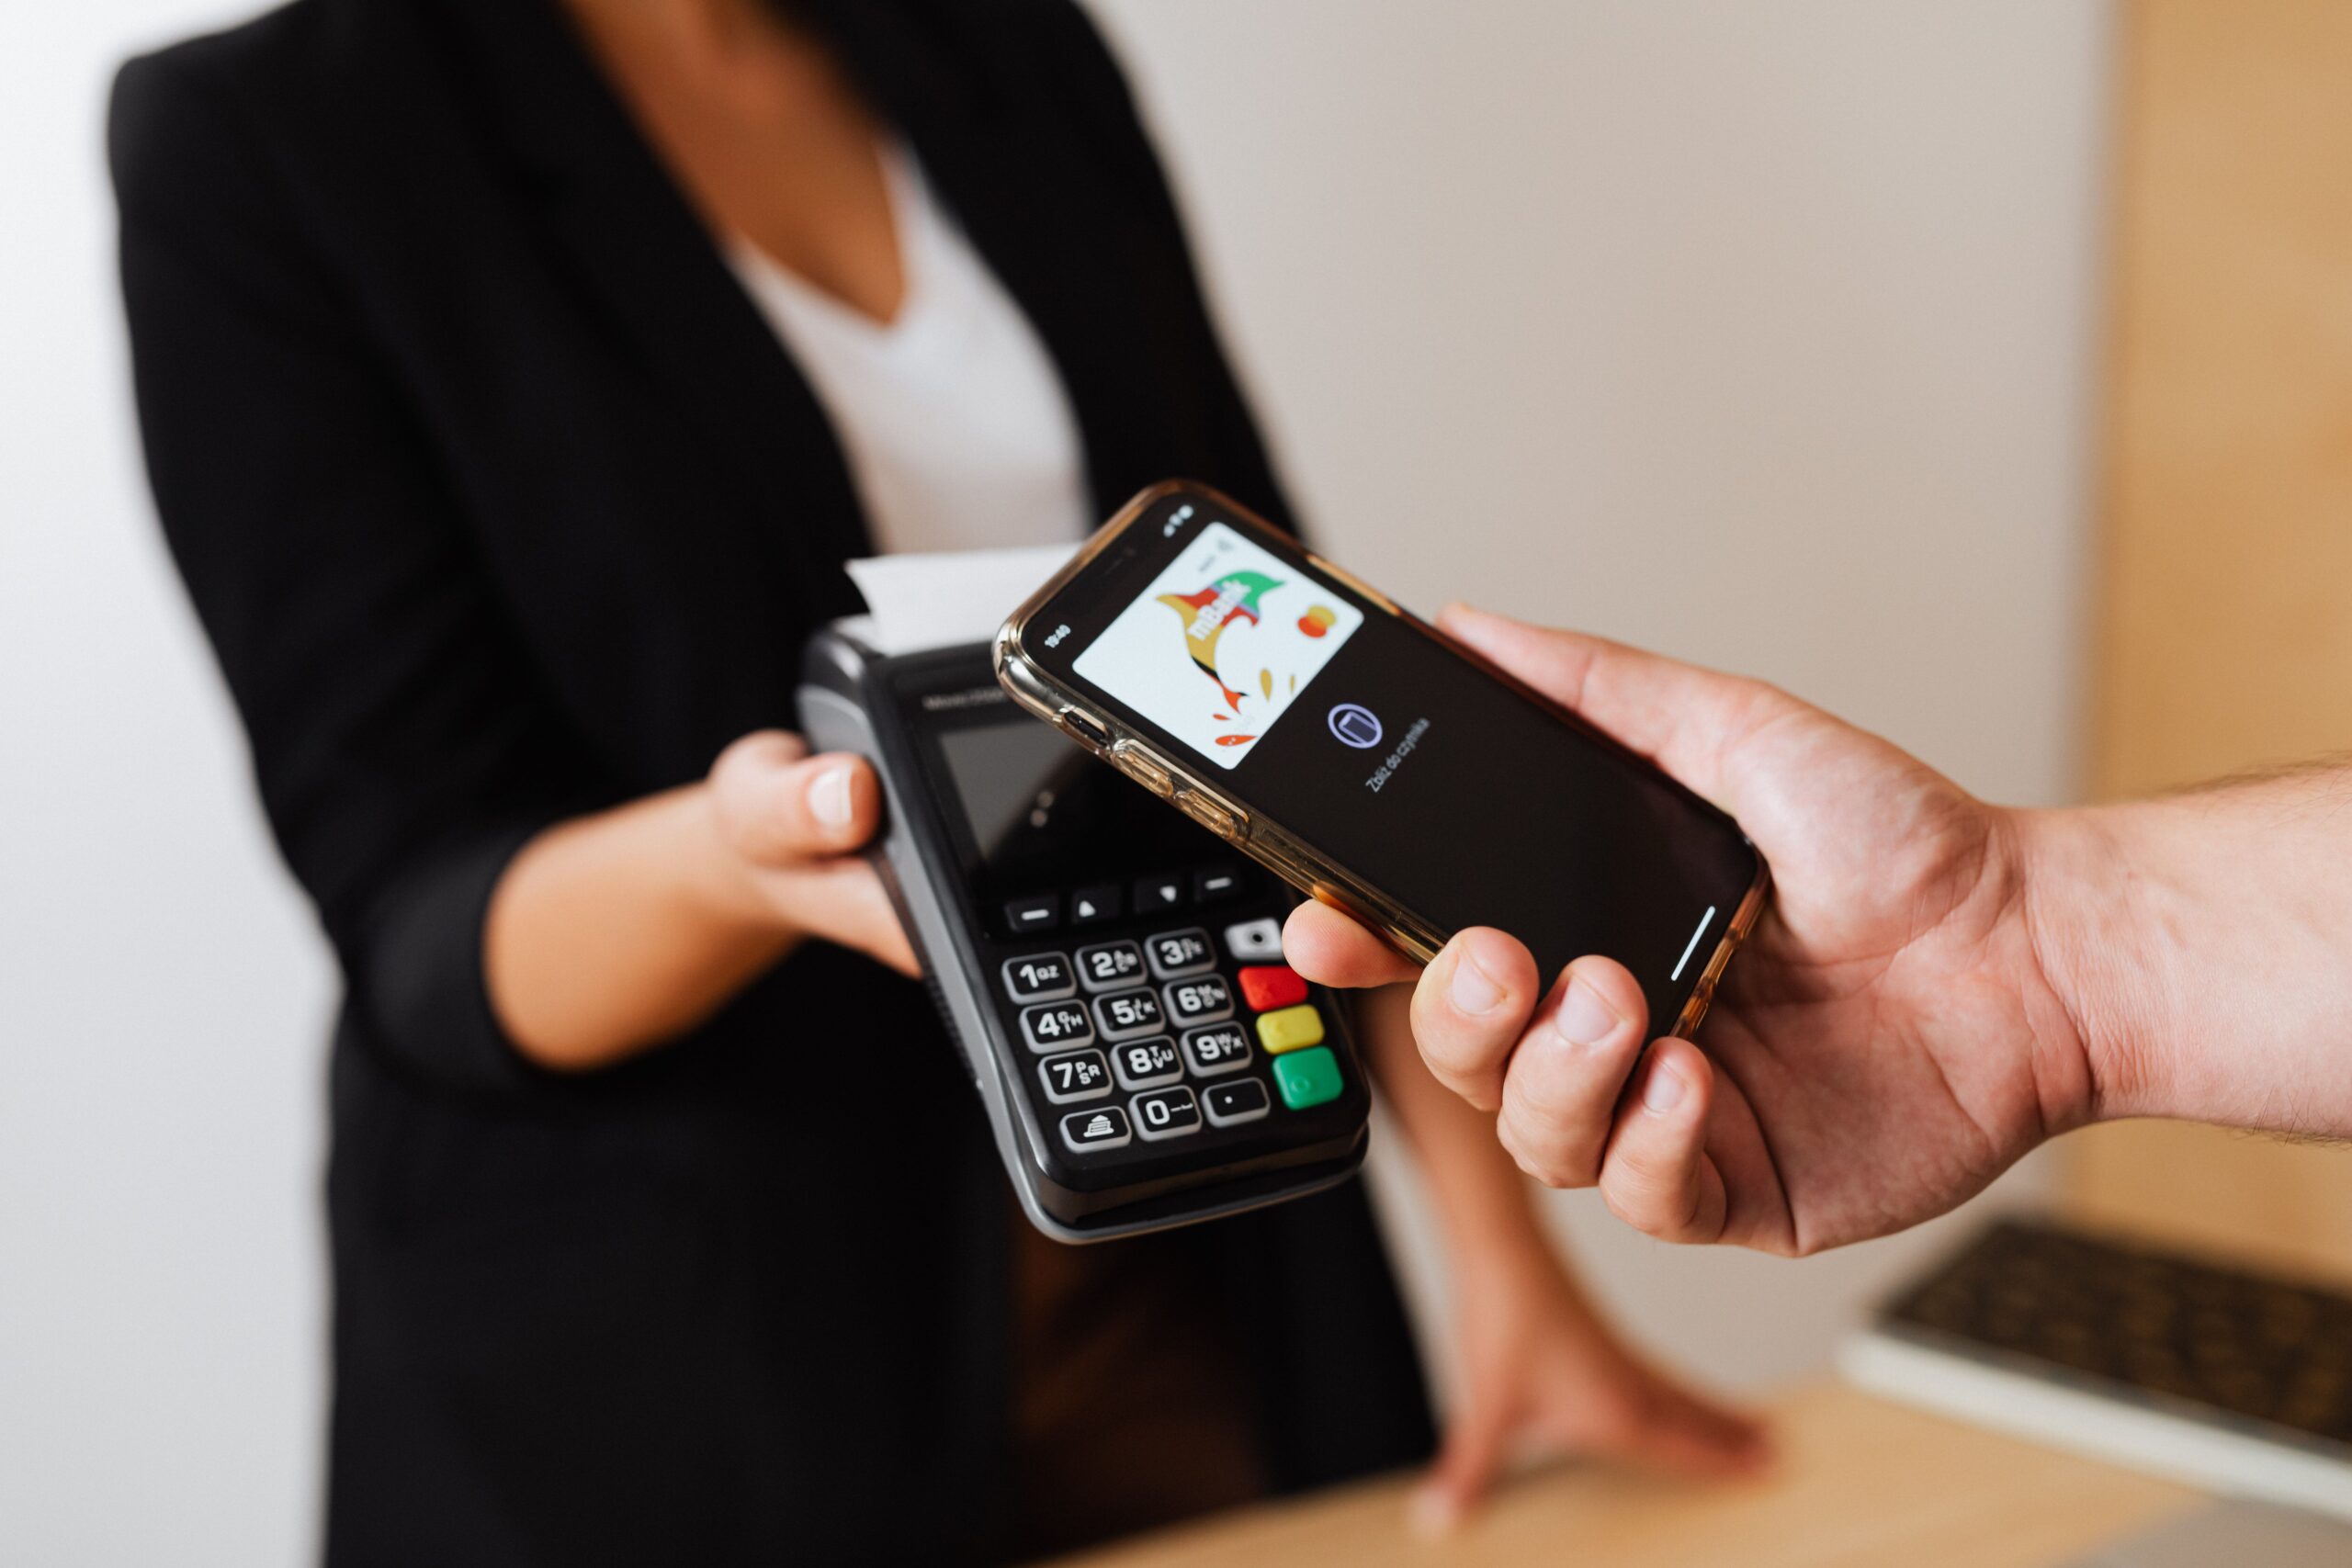
The global business landscape is undergoing one of the most significant transformations in modern economic history as cashless transactions rapidly become the preferred method of payment for businesses and consumers alike. What was once considered a futuristic concept has now evolved into an everyday reality, driven by technological innovation, changing consumer behavior, and the increasing demand for speed, convenience, and financial transparency. Across developed and emerging markets, companies of all sizes are embracing digital payment systems to remain competitive, improve operational efficiency, and meet the expectations of an increasingly connected customer base. As digital wallets, mobile banking applications, contactless cards, QR code payments, and online payment gateways continue to gain widespread acceptance, an important question now confronts business owners everywhere: Is your company truly ready for the cashless economy?
For decades, physical cash served as the backbone of commercial activity, offering simplicity and universal acceptance. However, advances in financial technology have fundamentally changed how businesses receive payments, manage finances, and interact with customers. Today, a growing number of consumers rarely carry significant amounts of cash, preferring instead to complete purchases with smartphones, debit cards, credit cards, wearable devices, or digital wallets. This shift has accelerated in recent years as businesses increasingly recognize that offering multiple electronic payment options is no longer a luxury but a necessity for attracting and retaining customers.
The rapid expansion of e-commerce has played a pivotal role in accelerating the move toward cashless business operations. Online shopping platforms have transformed consumer expectations by allowing customers to purchase goods and services from virtually anywhere in the world with just a few clicks. As digital commerce continues to grow, businesses that fail to provide secure and convenient electronic payment options risk losing customers to competitors that offer smoother and more flexible purchasing experiences. Even traditional brick-and-mortar retailers are investing heavily in modern payment infrastructure to accommodate evolving customer preferences and ensure seamless transactions both online and offline.
Small and medium-sized enterprises are among the biggest beneficiaries of this financial transformation. Digital payment technologies have lowered barriers to entry by making sophisticated payment systems affordable and accessible to businesses with limited resources. Entrepreneurs can now accept payments through mobile applications, payment terminals, QR codes, and cloud-based point-of-sale systems without making substantial investments in expensive banking infrastructure. This accessibility has empowered countless startups and local businesses to compete more effectively in both domestic and international markets.
Beyond customer convenience, cashless operations deliver substantial operational advantages for businesses. Managing large volumes of physical cash often involves significant administrative burdens, including counting money, reconciling daily sales, transporting deposits, and implementing security measures to prevent theft or fraud. Digital payments streamline these processes by automatically recording transactions, reducing human error, improving accounting accuracy, and simplifying financial reporting. Business owners gain access to real-time financial data that supports better decision-making, inventory management, budgeting, and long-term strategic planning.
According to financial analysts, businesses that embrace digital payment systems also strengthen their ability to understand customer behavior. Electronic transactions generate valuable data that can reveal purchasing patterns, peak sales periods, product preferences, and customer demographics. This information enables companies to develop more targeted marketing campaigns, personalize customer experiences, optimize pricing strategies, and forecast future demand with greater precision. Data-driven decision-making has become one of the defining characteristics of successful modern businesses operating in highly competitive markets.
Security remains another compelling factor driving the adoption of cashless business models. While no payment system is entirely immune to risk, advances in encryption, tokenization, biometric authentication, and artificial intelligence have significantly enhanced the protection of digital financial transactions. Financial institutions and payment providers continue investing heavily in fraud detection technologies capable of identifying suspicious activities in real time, helping businesses reduce financial losses while increasing customer confidence. Companies that implement secure payment infrastructure not only protect their revenue but also strengthen their reputation in an era where consumer trust has become a valuable competitive asset.
Despite these advantages, the transition to cashless operations is not without challenges. Cybersecurity threats continue to evolve alongside technological innovation, requiring businesses to invest in robust digital security measures, employee training, and continuous system updates. Data breaches, phishing attacks, ransomware, and payment fraud remain serious concerns for organizations handling sensitive financial information. Business leaders must therefore recognize that adopting digital payments also involves developing comprehensive cybersecurity strategies that safeguard customer information and maintain regulatory compliance.
Another consideration is financial inclusion. While digital payment adoption continues to grow worldwide, some consumers still rely heavily on physical cash due to limited access to banking services, internet connectivity, or digital literacy. Businesses operating in diverse communities must carefully balance innovation with accessibility by understanding the needs of their customer base before implementing fully cashless models. In many markets, hybrid payment systems that accommodate both electronic and cash transactions continue to provide the greatest flexibility while ensuring no customer segment is excluded.
Industry experts note that government policies and regulatory reforms are also accelerating the transition toward digital economies. Many countries are investing in national payment infrastructure, promoting financial technology innovation, and encouraging electronic transactions to improve tax transparency, reduce informal economic activity, and strengthen economic efficiency. Central banks are exploring digital currencies, while commercial banks continue expanding instant payment networks that make electronic transfers faster, more affordable, and increasingly accessible to businesses and consumers alike.
According to DDM News, one of the defining characteristics of companies successfully navigating the cashless revolution is their willingness to embrace continuous technological adaptation. Rather than viewing digital transformation as a one-time investment, forward-thinking organizations recognize it as an ongoing process requiring regular upgrades, employee training, customer education, and strategic planning. Businesses that remain proactive are better positioned to respond to changing consumer expectations while maintaining operational resilience in an increasingly digital marketplace.
The rise of financial technology has also fueled remarkable innovation among payment service providers. Artificial intelligence now assists in fraud prevention, automated customer support, credit risk assessment, and personalized financial services. Contactless payment technologies continue expanding into transportation, healthcare, education, hospitality, and entertainment industries, creating new opportunities for businesses to improve customer experiences while reducing transaction times. The integration of payment systems with inventory management, accounting software, and customer relationship management platforms further enhances operational efficiency, allowing companies to manage multiple aspects of their business through unified digital ecosystems.
Business leaders preparing for the future understand that investing in cashless infrastructure extends beyond purchasing payment terminals or integrating online payment gateways. It requires developing a comprehensive digital strategy that includes cybersecurity readiness, regulatory compliance, employee training, customer communication, reliable internet connectivity, and contingency planning for technical disruptions. Organizations that approach digital transformation strategically are more likely to achieve sustainable long-term success than those adopting new technologies without adequate preparation.
Consumer expectations continue evolving rapidly, particularly among younger generations who increasingly value convenience, speed, and seamless digital experiences over traditional payment methods. Businesses that fail to meet these expectations risk appearing outdated and less responsive to modern market demands. Conversely, companies that prioritize innovation, convenience, and customer satisfaction often strengthen their competitive advantage while expanding their reach into new markets and customer segments.
As emphasized throughout this exclusive report by DDM News, the rise of cashless business represents far more than a technological trend it signals a fundamental shift in how commerce operates in the twenty-first century. Organizations that embrace secure digital payment solutions, invest in technological resilience, prioritize customer trust, and remain adaptable to continuous innovation will be better equipped to thrive in an increasingly digital economy. While the journey toward a fully cashless future may vary across industries and regions, one reality has become increasingly clear: businesses that prepare today will be the ones best positioned to lead tomorrow’s marketplace. The cashless revolution is no longer approaching; it is already here, and the companies willing to evolve alongside it stand to unlock new levels of efficiency, growth, and long-term success.